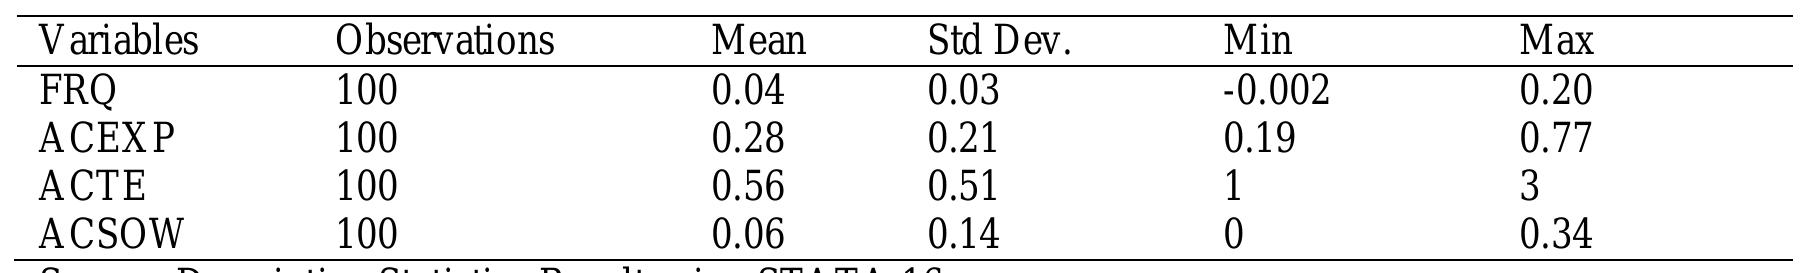
Table 1. Descriptive Statistics of the Variables Table 1 present the descriptive statistics for the dependent and the independent variables. Discretionary accrual which is the explained variable of the study has a minimum value of -0.002 and a maximum value of 0.20. The mean value of the DAC is 0.04 with a standard deviation of 0.03. This discloses that there is a low discrepancy in the nature in which the manufacturing firms engaged in earnings management. The table also implies that the average figure for audit committee expertise is 0.28 and the standard deviation is 0.21. This implies that on average about 28% of the audit committee members are financial expertise and these guide is similar in the sampled manufacturing firms as shown in the standard deviation figure. The minimum and the maximum value is 0.19 and 0.77 respectively.
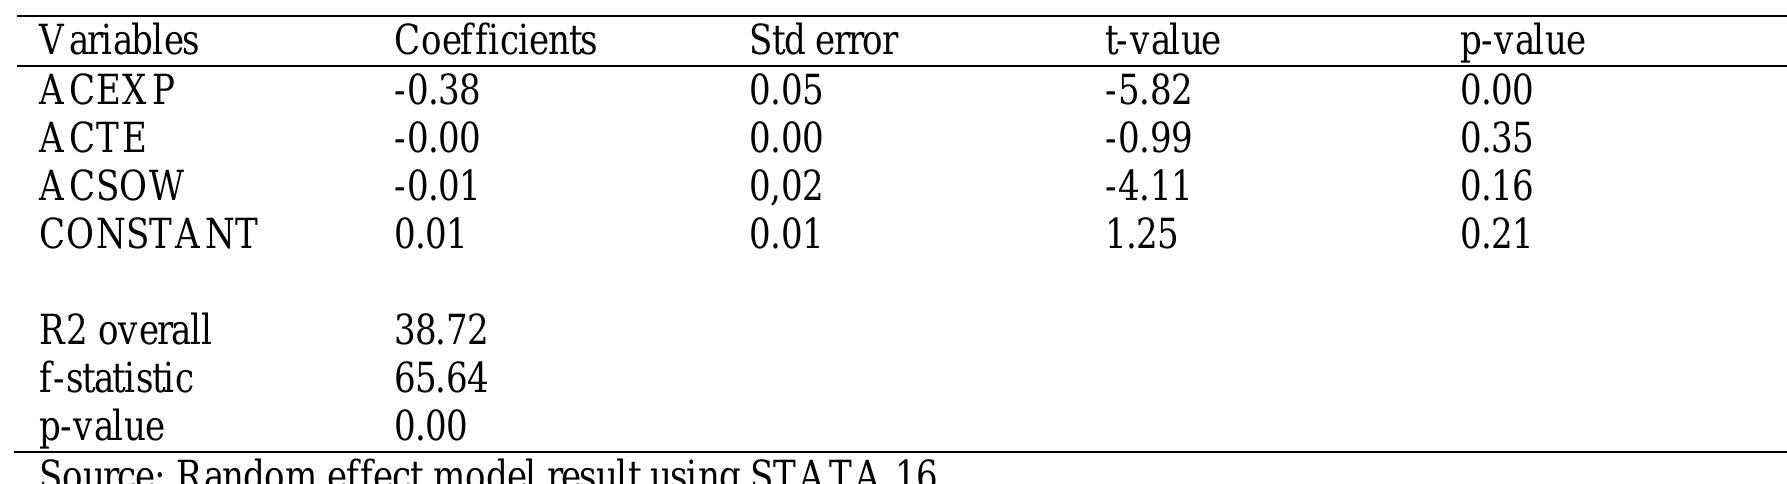
Abstract: This study evaluates the audit committee impact on earnings management of listed manufacturing companies in Nigeria. The study uses secondary data which were extracted from ten (10) sampled manufacturing firms listed in the Nigerian Stock Exchange (NSE) for the period 2010-2019. The study used Random Effects Model (REM) for the analysis of data. The results showed that financial expertise of audit committee has significant negative impact on earnings management while audit committee tenure has an insignificant negative impact on earnings management. Furthermore, share ownership of audit committee has significant negative impact on earnings management. The study therefore, concludes that both the audit committee expertise and share ownership of audit committee enhance the financial reporting quality of manufacturing firms in Nigeria. Based on the impact of members of audit committee with financial expertise, the study recommends among others that, the board should ensure appointing the sufficient audit committee members that are experts on financial matters. Similarly, the study also recommends the enclosure of more members with substantial shareholdings in the audit committee. This can enhance their willingness to protect their investment and helps in proper monitoring and supervision, thereby reducing earnings management.